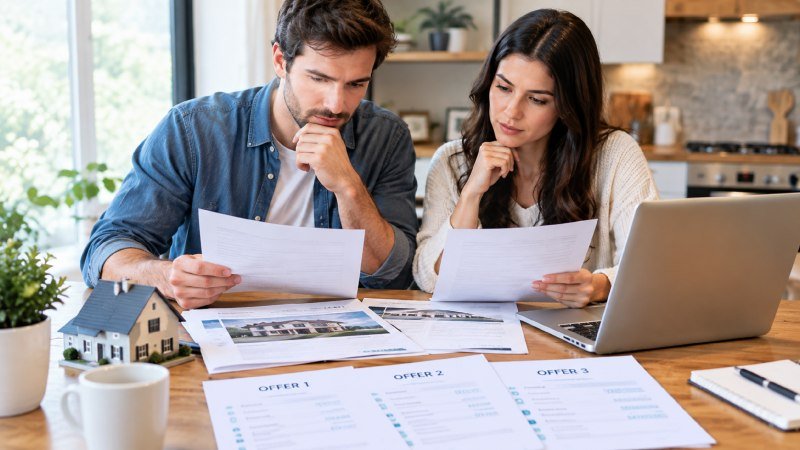
Selling a property can feel straightforward until multiple offers arrive with different prices and terms. A higher offer may appear more attractive at first, but the amount a buyer proposes is only one part of the transaction. Financing, contingencies, and other conditions can affect how smoothly the sale moves forward.
For homeowners looking to sell their house for cash, understanding the details can make it easier to compare each offer based on its overall terms rather than the purchase price alone.
Key Factors to Consider When Comparing Property Offers
Look Beyond the Offered Purchase Price
The purchase price is an important starting point, but it does not tell the entire story. An offer with a higher number may include conditions, credits, repair requests, or other expenses that reduce the amount the homeowner ultimately receives.
Instead of comparing the headline figures alone, review what each buyer is asking the seller to contribute or complete before closing.
Review the Financing and Proof of Funds
The buyer’s financing can affect how confidently a homeowner can approach the transaction. A financed offer may depend on mortgage approval, underwriting, and an appraisal, while a cash offer does not rely on mortgage financing.
Homeowners should review proof of funds provided with an offer. This can help establish whether the buyer appears prepared to meet the financial requirements of the purchase.
Compare Contingencies and Conditions
Contingencies give buyers opportunities to cancel the transaction or renegotiate under specific circumstances. Common examples include inspection, appraisal, financing, and the sale of another property.
Each contingency can affect the transaction differently. Comparing the number and type of contingencies in each offer can help homeowners understand where additional negotiations or delays could arise.
Consider the Closing Timeline
The proposed closing date should also fit the homeowner’s circumstances. Some sellers may need additional time to move, while others may prefer to complete the sale quickly because of financial or personal plans.
A flexible buyer may be willing to work around the seller’s preferred timeline, while another offer may require a specific closing date. Comparing these timelines can help homeowners determine which offer fits their plans without creating unnecessary scheduling problems.
Account for Repairs and Other Potential Costs
Repair requests, seller credits, and other concessions can change the financial outcome of an offer. A buyer may agree to a certain purchase price but request that the homeowner complete repairs or provide a credit before closing.
These expenses should be considered alongside the offered price. Looking at the expected costs associated with each offer provides a more realistic comparison and helps prevent a seller from choosing an offer that appears stronger simply because its initial price is higher.
Evaluate the Risk of the Deal Falling Through
Every real estate transaction carries some level of uncertainty, but the terms of an offer can affect how that uncertainty is managed. Financing approval, inspection findings, and other conditions may create opportunities for a transaction to be delayed, renegotiated, or canceled.
Homeowners should consider how much of the transaction depends on events that have not yet been completed. Understanding those steps can make it easier to compare the practical certainty of different offers.
Read the Entire Offer Before Making a Decision
Before accepting an offer, homeowners should review the complete agreement rather than relying on the purchase price or a summary of the main terms. Deadlines, earnest money provisions, contingencies, requested concessions, and other conditions can all affect the transaction.
If any provision is unclear, getting an explanation before signing can prevent misunderstandings later.
Final Thoughts
Evaluating multiple property offers requires a broader view than simply choosing the highest number. Purchase price, financing, contingencies, closing dates, repair requests, and additional costs should all be considered together. A careful comparison gives homeowners a clearer understanding of what each offer involves and how it fits their priorities.
For homeowners interested in a direct cash sale, Bridgehaven Homes provides an alternative to the traditional listing process. The company buys homes directly in their current condition, with no agent commissions or listing fees for sellers. It also offers flexible closing dates, with qualifying transactions able to close in as little as seven days.
Frequently Asked Questions
What should homeowners compare when evaluating multiple offers?
Homeowners should compare the purchase price, financing, contingencies, closing timeline, repair requests, and other costs associated with each offer.
Is the highest offer always the best offer?
Not necessarily, because a higher purchase price may come with additional conditions, repair requests, or seller concessions. The complete terms should be reviewed before determining how an offer fits the seller’s needs.
What contingencies should homeowners look for in an offer?
Common contingencies include inspection, appraisal, financing, and the sale of another property. Homeowners should understand how each condition could affect the timeline, negotiations, or ability to complete the sale.
How does the closing date affect an offer?
The closing date determines when the sale is expected to be completed and funds are transferred. It should be compared with the homeowner’s moving plans, financial needs, and other timing requirements.
Should repair requests be considered when comparing offers?
Yes. Repair requests, seller credits, and other concessions can reduce the financial benefit of an offer, so they should be considered alongside the purchase price.